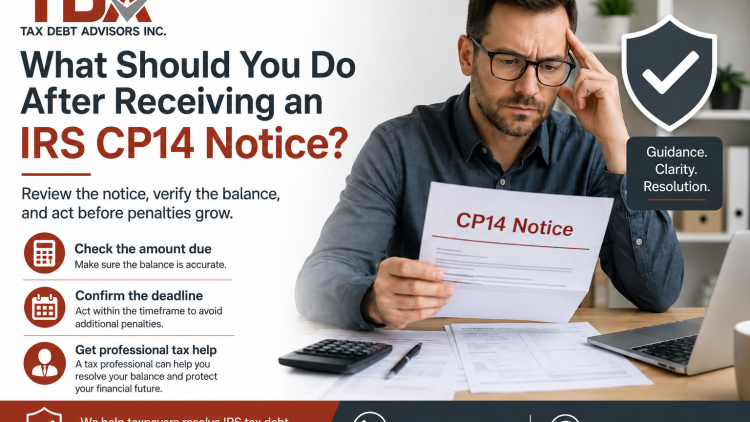
An IRS CP14 notice says you have a balance due. Learn how to verify the amount, check recent payments, and respond before the deadline.
Written by Craig B

What Should You Do After Receiving an IRS CP14 Notice?

Student loans can have various implications for federal taxes, including potential deductions, credits, and consequences for repayment. Here are some key points to consider regarding student loans and federal taxes:

  1. Student Loan Interest Deduction: Taxpayers who have paid interest on qualified student loans may be eligible to deduct up to $2,500 of the interest paid on their federal income tax return. This deduction is available even if the taxpayer does not itemize deductions, making it accessible to many taxpayers. However, there are income limitations and other eligibility criteria that must be met to claim this deduction.
  2. Education Tax Credits: Taxpayers who are paying for higher education expenses, including student loan interest, may be eligible for education tax credits such as the American Opportunity Tax Credit (AOTC) or the Lifetime Learning Credit (LLC). These credits can help reduce the amount of tax owed or result in a refund if the credits exceed the taxpayer’s tax liability.
  3. Income-Driven Repayment Plans: Borrowers who are enrolled in income-driven repayment plans (IDRs) for their federal student loans may have a portion of their outstanding loan balance forgiven after making qualifying payments for a certain period. However, the forgiven amount may be considered taxable income in the year it is discharged, potentially resulting in a higher tax liability for the borrower.
  4. Taxability of Loan Discharges: In certain circumstances, such as total and permanent disability or death, federal student loans may be discharged, meaning the borrower is no longer required to repay the remaining balance. However, the discharged amount may be considered taxable income unless an exception applies.
  5. Employer Student Loan Repayment Assistance: Some employers offer student loan repayment assistance as a benefit to employees. Under current law, employer contributions to employee student loans of up to $5,250 per year may be excluded from the employee’s taxable income, providing potential tax savings.
  6. Tax Withholding Adjustments: Borrowers who expect to have a significant tax liability due to forgiven student loan debt or other factors may need to adjust their tax withholding or make estimated tax payments to avoid underpayment penalties.

It’s important for borrowers to understand the tax implications of their student loans and to consult with a tax professional or financial advisor for personalized advice based on their individual circumstances. Additionally, tax laws and regulations may change over time, so borrowers should stay informed about any updates that may affect their tax situation.

Tax Settlement in Mesa, Arizona

If you need IRS Debt Help, Tax Debt Settlements or Tax Debt Advising in Phoenix, Mesa or anywhere else, Tax Debt Advisors can help! Give us a call at 480-926-9300 or fill out our contact form for a free consultation.
Are Car Accident Settlements Taxable
Written by webtechs

Are Car Accident Settlements Taxable?

A personal injury settlement often brings huge relief following a traumatic car crash. The amount can be used to cover lost wages or pay medical bills. Let’s take a look at how the Internal Revenue Service (IRS) views these accident settlements and which portions could be taxable.

Can Car Accident Settlements Be Taxed?

IRS Section 104 offers an exclusion from taxable income related to lawsuits, awards, and settlements. Under the Internal Revenue Code, the majority of personal injury settlements for physical injuries are not taxable.

This will include compensation for any hospital bills, medical treatments, surgeries, and physical therapy. Damages for pain and suffering or emotional distress directly connected to a physical injury are typically excluded from income.

Additionally, if your attorney fees are ultimately deducted from the non-taxable portion of the settlement, these fees are not taxable either.

Lost Income And Other Taxable Amounts

It’s important to note not all compensation is treated the same. For example, if your settlement includes damages for lost wages, this amount is usually taxed. This is due to the fact that the wages would’ve been taxed if they had been earned normally.

Punitive damages is another taxable category. This is awarded typically to punish intentional or reckless actions. While this is rarely done in car accident cases, these damages will be taxed. The same goes for interest that accrues on a settlement in between the time the case is resolved and the payment gets made.

Property damage compensation can be quite complex. If you receive money for vehicle repairs or replacements, the amount is not taxable if it does not exceed your car’s adjusted value. If the reimbursement exceeds the car’s value, however, the excess could be considered taxable.

Non-Economic Damages

Emotional distress creates another gray area in these cases. If the distress stems from a physical injury right after a car crash, it is usually tax-exempt. Compensation for trauma without physical harm can be taxable.

Most claims will combine different kinds of compensation. This can include lost wages, medical bills, emotional distress, and more.

Tax Settlement in Mesa, Arizona

If you need IRS Debt Help, Tax Debt Settlements or Tax Debt Advising in Phoenix, Mesa or anywhere else, Tax Debt Advisors can help! Give us a call at 480-926-9300 or fill out our contact form for a free consultation.
What Is a Tax Amnesty Program?
Written by Craig B

What To Do When IRS Tax Debt Starts Keeping You Up At Night

IRS tax debt has a way of getting into your head. A letter arrives, then another one. Maybe you owe more than you expected. Maybe old returns were never filed. Maybe penalties and interest have made the number feel impossible. At some point, the problem stops being only financial. It becomes stress.

The worst thing to do is panic. The second worst thing is to ignore it.

Start By Opening The IRS Notices

It sounds simple, but many people stop opening IRS mail because they are afraid of what it says. That only makes the situation harder. Notices can explain the tax year involved, the balance due, deadlines, appeal rights, missing returns, proposed changes, or collection action.

You do not have to understand every line by yourself. But you do need to know what the IRS is asking for and how urgent the deadline is.

Put every notice in one folder. Do not throw anything away. The paper trail matters.

File Missing Returns Before Chasing A Deal

If you have unfiled tax returns, those usually need attention before a real resolution can happen. The IRS wants current information before considering many collection options.

Back tax returns can feel embarrassing, but they are common. People fall behind after job changes, business problems, divorce, illness, self employment surprises, or simple fear. The important thing is to get accurate returns filed and stop the problem from growing.

A professional who handles back tax returns can help reconstruct records and bring the account closer to compliance.

Be Careful With Big Promises

Tax debt advertising can be loud. Some companies make it sound as if nearly everyone can settle for pennies on the dollar. That is not how the IRS works.

Some taxpayers may qualify for an offer in compromise. Others may need an installment agreement, currently not collectible status, penalty review, bankruptcy guidance from an attorney, or another route. The right answer depends on income, assets, expenses, tax years, compliance, and the IRS collection file.

A good tax professional should explain your actual options, not sell you a fantasy.

Work With The Person Handling Your Case

Tax debt is personal. You should know who is representing you, what they are doing, and what the next step is. Being passed from salesperson to call center to unknown case manager can make the process more frustrating.

Tax Debt Advisors works directly with taxpayers who need IRS debt help, back tax returns, and professional tax resolution guidance. The company emphasizes direct representation with Scott Allen E.A., rather than a sales driven process.

Get Help Before The IRS Gets Louder

If IRS tax debt is causing stress, do not wait for levies, liens, wage garnishment, or more notices before asking for help. Contact Tax Debt Advisors to discuss your tax debt, missing returns, and possible IRS resolution options with someone who can look at the real details.

References

Tax Debt Advisors
https://taxdebtadvisors.com/

Tax Debt Advisors About
https://taxdebtadvisors.com/about.html

IRS Payment Plans
https://www.irs.gov/payments/payment-plans-installment-agreements

IRS Offer In Compromise
https://www.irs.gov/payments/offer-in-compromise

IRS Taxpayer Bill Of Rights
https://www.irs.gov/taxpayer-bill-of-rights

Tax Settlement in Mesa, Arizona

If you need IRS Debt Help, Tax Debt Settlements or Tax Debt Advising in Phoenix, Mesa or anywhere else, Tax Debt Advisors can help! Give us a call at 480-926-9300 or fill out our contact form for a free consultation.
Who Is Responsible For Incorrect W2
Written by webtechs

Who Is Responsible For Incorrect W-2?

It’s always concerning whenever you receive a Form W-2 with inaccurate information. Errors on this form can lead to complications and delays with the Internal Revenue Service (IRS). Learn how you can correct information on this form below.

What Is The Employer’s Legal Obligation?

Under federal law, any individual or business that pays wages and withholds taxes is required to provide employees with a written wage statement. Typically, the deadline to furnish these forms to employees and the Social Security Administration is January 31. However, the deadline will fall to the next business day if January 31 happens to be on a weekend or holiday.

When an employer hires a third-party payroll system, they are usually still responsible for ensuring wage statements are filed properly and taxes are paid. The IRS will enforce these requirements by imposing penalties for late filing or incorrect statements.

Typically, fines will start at $60 per form and will increase based on how long the error takes to be corrected. Employers can also be penalized for incorrect or missing details on the form. Penalties can reach $660 per form with no cap on the total fine.

How Can An Employee Correct A W-2?

Once you receive your W-2, thoroughly review it to catch any possible errors. It’s suggested to compare all the information on the form to your own records. You’ll want everything to match, at this time.

Verify the following key areas on the form:

  • Make sure your name is spelled correctly.
  • Wage and salary figures match your own records.
  • Social Security number is correct.
  • Amounts withheld for federal, state, Social Security, and Medicare taxes match your records.

How To Request A Correction From Your Employer

The first move you should make when you notice any error on the form is to simply ask your employer to correct it. Form W-2c is the official document used to fix errors, which is a Corrected Wage and Tax Settlement. At this time, you should gather documentation, such as pay stubs and direct deposit statements, showing the correct figures.

Submitting this request in the written form will ensure there is a record of communication. In this request, you should clearly state which information is incorrect, while providing the correct numbers. When referencing the supporting documents, you ultimately make it easier for the employer to verify and make the requested changes.

What To Do If Your Employer Refuses To Cooperate

If it is the end of February and your employer has failed to provide a corrected form, you can contact the IRS for further help. The agency will then contact your employer to request the missing or corrected form. You will then be sent instructions detailing how you can proceed with the filing.

When reporting this issue to the IRS, have the following information ready:

  • Your name, address, and Social Security number.
  • Name of the employer, address, and phone number.
  • Your employment dates.
  • Estimate of your earned wages and the federal income tax withheld.

How To File Taxes With An Uncorrected W-2?

Even if you have yet to receive a corrected wage statement, you should always file your taxes on time. You can use Form 4852 as a substitute when the corrected form fails to arrive by the set deadline. This form allows you to report your estimated wages and withheld taxes based on your own yearly records.

When filing your return, make sure to attach Form 4852 to it. Using a substitute form can delay your return or refund as the IRS must verify your provided figures. If you receive a corrected form after filing that differs from your estimates, you are required to file an amended return using Form 1040-X.

Tax Settlement in Mesa, Arizona

If you need IRS Debt Help, Tax Debt Settlements or Tax Debt Advising in Phoenix, Mesa or anywhere else, Tax Debt Advisors can help! Give us a call at 480-926-9300 or fill out our contact form for a free consultation.
What Is a Tax Amnesty Program?
Written by Craig B

What Is a Tax Amnesty Program?

The federal and state governments offer tax amnesty programs, which are special, time-limited plans that give people the chance to settle their outstanding tax debts with big benefits. The goal of these schemes is to get people to voluntarily pay their taxes. They do this by giving people benefits like lighter sentences, no interest charges, or even protection from being charged. We will talk more about what tax relief programs are, how they work, and who can get help from them.

Tax Amnesty: What Is It?

A tax amnesty program lets people and businesses reveal income they didn’t report or underreported, fix mistakes they made when filing their taxes in the past, or settle their debts without having to pay the full penalties and interest that are usually involved with these actions. The goal of these schemes is to bring in more tax money.

One of the best things about these programs is that they start over. In essence, they let taxpayers fix their tax problems without fear of facing harsh penalties. Participants may have fines lowered or taken away depending on the program. They might also avoid going to jail for tax fraud or other crimes.

How tax cuts and waivers work

Tax pardon programs are not all the same, but most of them are set up in the same way. People who owe taxes are usually given a certain amount of time to come forward, file their reports, and pay any taxes that are due. People who do this get perks in return, such as fewer or no penalties. A lot of tax amnesty programs will forgive late payment penalties, failure-to-file penalties, and other charges that are linked to penalties.

No interest to pay. Some programs also waive some or all of the interest, which lowers the total tax bill.
Protection from being charged. One important part of many pardon programs is that people who have broken the law with their taxes in the past won’t be prosecuted. This can be a big reason for people to come forward.

Depending on the area that is giving the amnesty, the program could cover a lot of different taxes, like sales taxes, income taxes, or property taxes.

Who Would Benefit from a Tax Amnesty?

Tax amnesty schemes help a lot of different types of taxpayers. People or companies that are behind on their taxes because of money problems, forgetfulness, or other issues may be able to get help. People who didn’t file tax returns in the past but now want to can do so without having to pay the full fines. If you have underreported your income, either by accident or on purpose, taking part in an amnesty program can save you from the legal and financial problems that come with being inspected or charged. Many businesses have not paid their sales taxes or other taxes to the government. Tax amnesty lets these companies settle their debts.

The Bad Things About Tax Amnesty Plans

There are clear benefits to tax pardon programs, but there are also some possible downsides to think about. One is that they have a small opening. People who pay taxes need to act quickly to get the rewards. Also, some amnesty programs require people who take part to say so in public, which could hurt a business’s image. Also, there is no promise of more services in the future. If you don’t take advantage of an amnesty program when one is offered, the government might not offer another one in the future.

What To Do If You Owe Taxes

Thankfully, there are numerous options if you cannot pay your entire tax bill when it’s due. Here are a few payment options for you to consider:

  • Sign up for an IRS installment plan.
  • Apply for a full-time agreement if you are able to pay taxes within 120 days.
  • Make an offer in compromise.
  • Consider a loan or other financing options to make tax payments.

It’s crucial to stay informed about your tax obligations and ensure accurate and timely filing and payment of taxes. If you find yourself owing taxes, it’s advisable to address the issue promptly by filing your return or payment, seeking professional tax assistance, or exploring options such as installment agreements, Offer in Compromise, or penalty abatement if you’re unable to pay the full amount owed.

Tax Settlement in Mesa, Arizona

If you need IRS Debt Help, Tax Debt Settlements or Tax Debt Advising in Phoenix, Mesa or anywhere else, Tax Debt Advisors can help! Give us a call at 480-926-9300 or fill out our contact form for a free consultation.

Student Loans and Federal Taxes in 2025: What Arizona Borrowers Need to Know
Written by Craig B

Student Loans and Federal Taxes in 2025: What Arizona Borrowers Need to Know

If you’re paying back student loans or waiting for help, it’s a good idea to know how those loans will affect your federal taxes in 2025. Tax laws about student loans have changed a lot in the last several years. As an Arizona taxpayer, it’s crucial to stay up to date so you don’t miss out on important deductions or be hit with surprise tax liabilities.

Let’s go over what’s new this year, what’s still the same, and how to answer tax inquiries about student loans with confidence.

1. Student Loan Interest Deduction

The student loan interest deduction is still available for 2025. Borrowers can deduct up to $2,500 in interest paid during the year. Even if you don’t itemize your deductions, this one can cut your taxable income.

To Be Eligible:

You can only use your loan for certain types of college costs.

You have to pay the loan back by law.

Your modified adjusted gross income (MAGI) must be less than the phase-out limits, which change every year to keep up with inflation.

The deduction slowly goes away if you make more than specified amounts. Most Arizona taxpayers with middle-class incomes still qualify. Your loan servicer will send you Form 1098-E, which shows how much interest you paid. Be sure to include it when you file.

2. Forgiveness and Cancelation

This is the largest transformation that has happened in a long time. Most federal student debt forgiveness, whether it’s through income-driven repayment (IDR) plans, Public Service debt Forgiveness (PSLF), or even some disability discharges, won’t be taxed at the federal level until 2025.

This implies that if you have an approved program that forgives your outstanding balance, the IRS won’t count it as taxable income. But if Congress doesn’t continue this rule, forgiven balances after 2025 may be taxable again.

Arizona is lucky since it follows the same rules as the federal government on this subject, thus state taxes usually won’t apply either. Always check before you file, because the rules in each state may change from year to year.

3. Refunds and Loans That Have Gone Bad

If you don’t pay back your student loans, the federal government can take some of your tax refunds to get the money back. This process, known as a Treasury Offset, applies to refunds like your income tax or even your Social Security payouts.

Offsets were put on hold during the COVID-era payment freeze. But as of 2025, routine collecting operations have started up again. If you think you might be at risk, get in touch with your loan servicer or go to studentaid.gov to learn more about rehabilitation or consolidation before tax season.

Tax Debt Advisors in Mesa, Arizona, often helps clients deal with or avoid offsets by talking to the IRS and setting up payment plans.

4. Tax and IDR Plans

Your monthly cost on an IDR plan is based on your income and the number of people in your family. You have to recertify your income every year, and you usually do this with information from your tax return.

Your payment amount may depend on your filing status:

When you file jointly as a married couple, both of your incomes are counted.

If you’re married and filing separately, only your income counts for most IDR plans.

Picking the appropriate file status can lower your monthly payment, but it could also raise your tax burden. This is where a professional can help. An Arizona tax advisor can model both results to discover the optimum balance.

5. Tax Experts Can Help

It’s not always clear how student loans and taxes are related. A professional who knows what they’re doing can:

Check to see if you may deduct the interest on your loan.

Find out if forgiveness will be taxable in your case.

If you’re behind on payments, keep your refund safe.

Advise on the best filing status for IDR recertification.

Tax Debt Advisors can help you figure out all the nuances so that your 2025 tax return shows all the benefits and avoids any unexpected debts if you live in Arizona.

In short, student loans can affect your taxes in several ways, such as how much you can deduct and how you plan to pay them back. If you know how the 2025 rules work, you’ll keep more money and follow both federal and Arizona tax regulations.

Keywords: student loans 2025, student loan interest deduction, student loan forgiveness taxes, student loan offset, IRS student loans, tax refund offset, Arizona tax help, Tax Debt Advisors, federal taxes and student loans, IDR plan taxes, Public Service Loan Forgiveness taxes, Arizona tax advisor, tax help Mesa AZ

Tax Settlement in Mesa, Arizona

If you need IRS Debt Help, Tax Debt Settlements or Tax Debt Advising in Phoenix, Mesa or anywhere else, Tax Debt Advisors can help! Give us a call at 480-926-9300 or fill out our contact form for a free consultation.

What Is a Tax Amnesty Program?
Written by webtechs

Why Do I Owe Taxes This Year?

There are many reasons why you might owe the Internal Revenue Service this year. It’s certainly possible to owe taxes even when you have withheld money from your paycheck all year.

Why Do I Owe Taxes?

Because everyone’s situation is unique, there are several different reasons why you may owe money on your taxes. A few common reasons are outlined below.

1. Failing To File

Failure to file on time is a common reason why you’ll end up owing taxes. State tax dues will vary. Whenever you file late and don’t apply for an extension on time, you can incur late fees and interests that will increase your tax bill. If you are wondering why you still owe taxes this year, it’s certainly possible that you submitted a tax return after the due date.

2. Not Withholding Enough From Your Paycheck

The amount that’s taken out of your paycheck each year is an estimate of what you will owe when it comes time to file taxes. You will receive a tax refund if you overpay. If you do not pay enough throughout the year, though, you will end up with a bill come tax season.

3. Tax Code Changes

Recent tax code changes will undoubtedly impact how much you’ll owe in taxes. If you expect to receive a refund each season, it may not be the case with new tax laws put in place. When the IRS updated its tax brackets, it’s possible you were put into a new category, altogether.

4. Changes In Deductions

If you didn’t qualify for typical deductions and credits you expected, then you may owe taxes this year. For instance, the earned income tax credit comes with annual limits. If you have made more money this year than in previous tax years, you may not qualify. Many parents will take advantage of the child tax credit, which comes with income limits and age restrictions.

5. Higher Income

Receiving higher pay this year will mean you are going to pay more in taxes. If you worked more hours while getting paid hourly or a salary gets raised, you could have been bumped into a higher tax bracket.

6. Significant Life Changes

All sorts of life changes can factor into your tax situation. One big change that can raise your tax burden is when your children start to get older. For instance, once your children are 17 years or older, you cannot claim the child tax credit.

While you’re no longer able to claim the child tax credit, you can still claim your children as dependents and claim a few other tax credits on your tax return.

7. You Owe Capital Gains Taxes

If you bought and sold investments for either a profit or loss, which includes anything from single stocks to cryptocurrency, you must report those gains or losses on your tax return.

With a capital gains tax, short-term capital gains are taxed at the normal income tax rate. Long-term gains, however, are taxed at a lower rate.

What To Do If You Owe Taxes

Thankfully, there are numerous options if you cannot pay your entire tax bill when it’s due. Here are a few payment options for you to consider:

  • Sign up for an IRS installment plan.
  • Apply for a full-time agreement if you are able to pay taxes within 120 days.
  • Make an offer in compromise.
  • Consider a loan or other financing options to make tax payments.

It’s crucial to stay informed about your tax obligations and ensure accurate and timely filing and payment of taxes. If you find yourself owing taxes, it’s advisable to address the issue promptly by filing your return or payment, seeking professional tax assistance, or exploring options such as installment agreements, Offer in Compromise, or penalty abatement if you’re unable to pay the full amount owed.

Tax Settlement in Mesa, Arizona

If you need IRS Debt Help, Tax Debt Settlements or Tax Debt Advising in Phoenix, Mesa or anywhere else, Tax Debt Advisors can help! Give us a call at 480-926-9300 or fill out our contact form for a free consultation.

Student Loans and Federal Taxes in 2025: What Arizona Borrowers Need to Know
Written by Craig B

Student Loans and Federal Taxes 2024

Student loans can have various implications for federal taxes, including potential deductions, credits, and consequences for repayment. Here are some key points to consider regarding student loans and federal taxes:

  1. Student Loan Interest Deduction: Taxpayers who have paid interest on qualified student loans may be eligible to deduct up to $2,500 of the interest paid on their federal income tax return. This deduction is available even if the taxpayer does not itemize deductions, making it accessible to many taxpayers. However, there are income limitations and other eligibility criteria that must be met to claim this deduction.
  2. Education Tax Credits: Taxpayers who are paying for higher education expenses, including student loan interest, may be eligible for education tax credits such as the American Opportunity Tax Credit (AOTC) or the Lifetime Learning Credit (LLC). These credits can help reduce the amount of tax owed or result in a refund if the credits exceed the taxpayer’s tax liability.
  3. Income-Driven Repayment Plans: Borrowers who are enrolled in income-driven repayment plans (IDRs) for their federal student loans may have a portion of their outstanding loan balance forgiven after making qualifying payments for a certain period. However, the forgiven amount may be considered taxable income in the year it is discharged, potentially resulting in a higher tax liability for the borrower.
  4. Taxability of Loan Discharges: In certain circumstances, such as total and permanent disability or death, federal student loans may be discharged, meaning the borrower is no longer required to repay the remaining balance. However, the discharged amount may be considered taxable income unless an exception applies.
  5. Employer Student Loan Repayment Assistance: Some employers offer student loan repayment assistance as a benefit to employees. Under current law, employer contributions to employee student loans of up to $5,250 per year may be excluded from the employee’s taxable income, providing potential tax savings.
  6. Tax Withholding Adjustments: Borrowers who expect to have a significant tax liability due to forgiven student loan debt or other factors may need to adjust their tax withholding or make estimated tax payments to avoid underpayment penalties.

It’s important for borrowers to understand the tax implications of their student loans and to consult with a tax professional or financial advisor for personalized advice based on their individual circumstances. Additionally, tax laws and regulations may change over time, so borrowers should stay informed about any updates that may affect their tax situation.

Tax Settlement in Mesa, Arizona

If you need IRS Debt Help, Tax Debt Settlements or Tax Debt Advising in Phoenix, Mesa or anywhere else, Tax Debt Advisors can help! Give us a call at 480-926-9300 or fill out our contact form for a free consultation.

Student Loans and Federal Taxes in 2025: What Arizona Borrowers Need to Know
Written by Craig B

Student Loans and Federal Taxes 2023

Student loans can have several implications for federal taxes in the United States. Here’s how they work with federal taxes:

  1. Student Loan Interest Deduction: One of the primary ways student loans affect federal taxes is through the student loan interest deduction. Borrowers who are repaying qualified student loans may be eligible to deduct the interest they’ve paid on those loans during the tax year. As of my last knowledge update in 2022, this deduction allows eligible taxpayers to reduce their taxable income by up to $2,500 per year, subject to income limitations. The loan must have been used for qualified education expenses, and there are income phase-out limits.
  2. Taxable Forgiveness: In some cases, if you have federal student loans that are forgiven through income-driven repayment plans or Public Service Loan Forgiveness (PSLF), the forgiven amount may be considered taxable income. This means you could owe taxes on the amount forgiven. However, certain forgiveness programs, like PSLF, offer tax-free forgiveness after 120 qualifying payments.
  3. Income-Driven Repayment Plans: Under income-driven repayment plans (e.g., Income-Based Repayment, Pay As You Earn, Revised Pay As You Earn), your monthly loan payments are calculated based on your income and family size. These plans can help make your payments more manageable, but they can also affect your tax liability. If your monthly payments are reduced, you may have a higher taxable income because your discretionary income is lower. This could result in a larger tax bill in some cases.
  4. Tax Credits for Education Expenses: While not directly related to student loans, there are federal tax credits available, such as the American Opportunity Credit and the Lifetime Learning Credit, that can provide tax benefits for qualified education expenses. You can’t double-dip by claiming these credits for the same expenses that you used to deduct student loan interest.
  5. State Tax Implications: In addition to federal taxes, it’s important to consider how student loans may impact your state income tax liability. State tax laws vary, and some states offer their deductions or credits for student loan interest.

It’s important to keep accurate records of your student loan payments, interest paid, and any relevant documents related to your loans. When it comes to tax matters related to student loans, it’s advisable to consult with a qualified tax professional or use tax software to ensure that you take advantage of available deductions and credits and understand the potential tax consequences of loan forgiveness. Additionally, it’s essential to stay informed about changes in tax laws and regulations that may affect student loans and tax liability.

Are you able file your taxes or comprehend what you owe Uncle Sam? There is a strong chance you’re confused about tax regulations. On the bright side, we’ve compiled a list of answers to 5 common tax questions you may be asking — including if you should hire a tax preparer, if you should file if you’re a college student, when you’ll receive your tax refund and more.

  1. Should I hire a tax preparer?

If you choose to hire a tax professional is subject to your comfort level with the tax-filing procedure and the convolution of your return. If you’re seeking a tax preparer with a greater degree of experience, consider a CPA or E.A. Both professionals are required pass specific exams to get licensed.

  1. What is the standard deduction?

The standard deduction is an allocated amount of money of which you aren’t taxed. The total of the standard deduction that you claim is subject on your tax status and the year that you’re filing. Taxes filed in 2019, the standard deduction $12,000 for filing single and $24,000 for married couples filing together.

  1. When will my tax refund get to me?

When your tax refund will get to you is subject on how and when you filed. According to the IRS 90% of federal tax refunds are distributed within twenty-one days, and details are usually available within a day from when the IRS receives an e-filed tax return or 4 weeks following them receiving a traditional paper return. Utilize the IRS Where’s My Refund? device and the IRS2Go app to track it.

  1. Should I file taxes if I’m enrolled in college?

Prior to you filing taxes as a student going to college, think about your income and if your parents will claim you as a dependent on their taxes. Students that earn less than $12,000 don’t need to file a tax return but might still gain from filing if taxes were withheld from their paycheck or want to claim specific tax benefits like the American opportunity tax credit.

  1. How can I get the largest tax refund this year?

To receive the largest tax refund this year, begin to think about your tax circumstances early, preferably prior to the tax year ending. Next, consider how to make the most out of deductions through itemizing if you’re able to, declare tax credits and deductions in which you qualify for and give to your retirement accounts. When your tax situation is convoluted, think about working with an experience tax preparer.

  1. How do I select the preferable tax-filing software?

When evaluating the preferable tax-filing software for your circumstance, think about the costs and services offered. A great place to begin is with the dozen software businesses that work alongside the IRS-affiliated Free File Alliance. They are IRS approved and satisfy specific security and privacy conditions.

  1. Who is established as a dependent on my taxes?

Dependents may include qualifying children, family members and other people that you support. Dependents need to satisfy certain age, income and housing conditions.

  1. How can I evade IRS tax scams?

Evade typical IRS tax scams by handling suspicious or out of left field communications from alleged IRS officials with a healthy suspicion. The IRS will usually reach out by regular mail first, so be cautious of e-mails, any texts or phone calls insisting to be from the IRS. Additionally, be vigilant for poor grammar, threats of calling the police and demands for payments through gift cards or wire transfers.

  1. Should I choose direct deposit?

Yes, when you want to get your tax refund as fast as possible, choosing direct deposit can be faster than, for instance, petitioning a check to be mailed out.

  1. Can I decrease my chances of getting audited?

To decrease the chance of a tax audit, make sure there are no errors, disclose all of your income, retain correct records and stay away from illegal or inappropriate tax moves like exaggerating charitable donations.

Whereas these answers to common tax questions may help you begin in fulfilling your tax responsibilities, you might still have questions as you start to file your return. If you see any questions you do not see on this list, contact us and we will be more than happy to answer them.

Tax Settlement in Mesa, Arizona

If you need IRS Debt Help, Tax Debt Settlements or Tax Debt Advising in Phoenix, Mesa or anywhere else, Tax Debt Advisors can help! Give us a call at 480-926-9300 or fill out our contact form for a free consultation.

IRS Online Payment Plans 2022
Written by Craig B

IRS Online Payment Plans 2023

If you are a qualified taxpayer or authorized representative (Power of Attorney) you can apply for a payment plan (including installment agreement) online to pay off your balance over time. Read on to learn more. You can a payment plan at: https://www.irs.gov/payments/online-payment-agreement-application

Qualification

Your specific tax situation will determine which payment options are available to you. Payment options include full payment, a short-term payment plan (paying in 120 days or less) or a long-term payment plan (installment agreement) (paying monthly).

You may qualify to apply online if:

  • Long-term payment plan (installment agreement): You owe $50,000 or less in combined tax, penalties and interest, and filed all required returns.
  • Short-term payment plan: You owe less than $100,000 in combined tax, penalties and interest.

If you are a sole proprietor or independent contractor, apply for a payment plan as an individual.

Note: Setup fees may be higher if you apply for a payment plan by phone, mail, or in-person. Get more information on other payment plan options and fees.

Payment Plan Applications

  • Name exactly as it appears on your most recently filed tax return
  • Valid e-mail address
  • Address from most recently filed tax return
  • Date of birth
  • Filing status
  • Your Social Security Number or Individual Tax ID Number (ITIN)
  • Based on the type of agreement requested, you may also need the balance due amount
  • To confirm your identity, you will need:
    • financial account number or
    • mobile phone registered in your name or
    • activation code received by postal mail (takes 5 to 10 business days)
  • If you previously registered for an Online Payment Agreement, Get Transcript, or any Identity Protection PIN (IP PIN), you should log in with the same user ID and password. You will need to confirm your identity by providing the additional information listed above if you haven’t already done so.

Costs

Pay Now

  • $0 setup fee
  • No future penalties or interest added

Pay amount owed in full today directly from your checking or savings account (Direct Pay)  or by check, money order or debit/credit card.
Fees apply when paying by card.

Short-term Payment Plan (120 days or less)

  • $0 setup fee
  • Plus accrued penalties and interest until the balance is paid in full

After applying for a short-term payment plan, you can pay the amount owed directly from your checking or savings account (Direct Pay) or by check, money order or debit/credit card.
Fees apply when paying by card.

Long-term Payment Plan (Installment Agreement)  (Pay monthly)

Pay monthly through automatic withdrawals

  • $31 setup fee (low income: setup fee waived)
  • Plus accrued penalties and interest until the balance is paid in full

Pay amount owed through Direct Debit (automatic payments from your checking account), also known as a Direct Debit Installment Agreement (DDIA). This is required if your balance is more than $25,000.
Pay each month (non-Direct Debit)

  • $149 setup fee (low income: $43 setup fee that may be reimbursed if certain conditions are met)
  • Plus accrued penalties and interest until the balance is paid in full

After applying for a long-term payment plan, pay amount owed through non-Direct Debit (not automated) monthly payments, including payments directly from your checking or savings account (Direct Pay) or by check, money order or debit/credit card.
Fees apply when paying by card.

Revise an Existing Payment Plan (Installment Agreement) or Reinstate After Default

  • $10 fee, which may be reimbursed if you are identified as low income and certain conditions are met.

IRS payment plans, also known as installment agreements, offer several advantages for taxpayers who owe back taxes but are unable to pay the full amount immediately. These payment plans are designed to help individuals and businesses fulfill their tax obligations while managing their financial circumstances. Here are some key advantages of IRS payment plans:

  1. Affordable Payments: Payment plans allow taxpayers to spread their tax debt over a specified period, making it more manageable to budget for regular payments. The IRS considers your financial situation when determining the monthly payment amount, which helps prevent financial hardship.
  2. Avoid Collection Actions: Entering into an IRS payment plan can help prevent more aggressive collection actions, such as wage garnishment, bank levies, or asset seizures. As long as you meet the terms of the agreement, the IRS generally suspends collection activities.
  3. Maintain Good Standing: Complying with an installment agreement helps you remain in good standing with the IRS. It demonstrates your commitment to resolving your tax debt and can positively impact your credit score and financial reputation.
  4. Flexible Terms: The IRS offers different types of payment plans, including short-term (120 days or less) and long-term (more than 120 days) plans. Taxpayers can choose the plan that best fits their financial situation.
  5. Reduced Penalties: If you enter into an installment agreement, you may be eligible to request a reduction in certain penalties, such as the failure-to-pay penalty. While interest continues to accrue on the unpaid balance, penalty relief can result in cost savings.
  6. Avoid Additional Costs: Failing to pay your tax debt on time can lead to additional costs in the form of penalties and interest. By entering into an IRS payment plan, you can stop the accrual of some penalties, potentially saving money in the long run.
  7. Structured Approach: Payment plans provide a structured approach to resolving your tax debt. You’ll have a clear payment schedule and a set date by which your debt will be fully paid, helping you stay on track.
  8. Avoid Negative Impact on Credit Score: While a tax lien may be filed when you enter into a payment plan, it’s typically not reported to credit bureaus. This means that your credit score may not be negatively affected, as long as you make your payments as agreed.
  9. Easier to Budget: Knowing the exact amount and due date of your monthly payments makes it easier to budget and plan your finances accordingly.
  10. Temporary Financial Relief: Payment plans can provide temporary financial relief, allowing you to address other financial priorities while still meeting your tax obligations.

Tax Settlement in Mesa, Arizona

If you need IRS Debt Help, Tax Debt Settlements or Tax Debt Advising in Phoenix, Mesa or anywhere else, Tax Debt Advisors can help! Give us a call at 480-926-9300 or fill out our contact form for a free consultation.

1 2