Learn how automatic IRS penalty relief works and when reasonable cause still matters.
Written by Craig B

IRS Automatic Exemption From Penalty Explained

IRS Automatic Exemption From Penalty: What Changed in 2026?

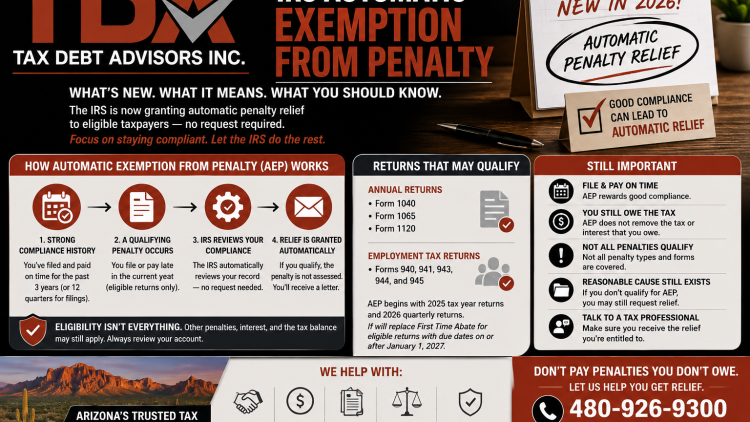
IRS penalty relief changed in 2026. For years, eligible taxpayers generally had to contact the IRS and request First Time Abate after a failure to file, failure to pay, or failure to deposit penalty appeared. The IRS is now moving toward Automatic Exemption from Penalty, known as AEP.

The change can prevent penalties from being assessed when the taxpayer has a strong compliance history. It does not erase the tax, remove every penalty, or replace reasonable cause relief.

AEP Rewards a Clean Compliance History

AEP is intended for taxpayers who filed and paid on time during the three prior years. Quarterly filers generally need 12 consecutive compliant quarters.

When an eligible taxpayer files or pays late in the current period, the IRS reviews the prior record. When the return and penalty type qualify, the applicable penalty is not assessed. The IRS sends a letter explaining that relief was granted.

Unlike traditional First Time Abate, the taxpayer does not need to telephone the IRS or submit a separate request to receive AEP.

Know Which Returns May Qualify

The IRS lists Forms 1040, 1065, and 1120 among the annual returns considered for AEP. Several employment tax returns can also qualify, including Forms 940, 941, 943, 944, and 945.

The automatic process begins with eligible 2025 tax year returns and 2026 quarterly returns. AEP will replace First Time Abate for eligible original returns with due dates on or after January 1, 2027.

Not every return is included. Estate tax returns, gift tax returns, many information returns, and penalties outside the covered categories may follow different rules.

The Relief Covers Specific Penalties

AEP applies to certain failure to file, failure to pay, and failure to deposit penalties. It does not cancel the tax shown on the return. Interest on unpaid tax still accrues, and penalties that are not eligible remain due.

Taxpayers should continue filing and paying as promptly as possible. Automatic relief is a safety net for qualifying compliance failures, not permission to delay future obligations.

A taxpayer may receive a penalty notice during the transition when the IRS has not yet applied AEP. The IRS advises people who believe they qualified to contact the agency.

First Time Abate Still Matters During the Transition

First Time Abate may still apply to eligible 2024 tax year returns, eligible 2025 quarterly returns, and some 2025 annual or 2026 quarterly returns processed before AEP begins for that account.

FTA is not automatic. The taxpayer normally needs to call the number on the notice or submit a written request. Older penalty years may also remain under the First Time Abate rules, so the tax period and processing date matter.

Reasonable Cause Is a Separate Route

A taxpayer who does not qualify for AEP may still request penalty relief based on reasonable cause. This route focuses on what happened, when it happened, how the event prevented timely compliance, and what the taxpayer did to correct the problem.

Serious illness, loss of records, natural disaster, or another event beyond the taxpayer’s control may support a request when the facts and documentation are strong. Lack of money by itself does not automatically establish reasonable cause.

The IRS may request hospital records, court documents, written correspondence, receipts, or other evidence. When telephone relief is not approved, Form 843 may be used in some cases to request abatement in writing.

Review the Entire IRS Balance

Penalty relief should be considered as part of the complete tax resolution. Removing a penalty can reduce the balance, but the remaining tax may still require full payment, an installment agreement, an offer in compromise, or hardship status.

Review each tax year separately. A taxpayer may qualify for automatic relief on one period, reasonable cause on another, and no penalty relief on a third.

Ask Tax Debt Advisors About IRS Penalty Relief

Tax Debt Advisors, Inc. has resolved IRS tax debt for Arizona individuals and businesses since 1977. Scott Allen, EA, can review penalty notices, compliance history, tax periods, supporting records, and the remaining balance to identify the relief options that apply. Call 480 926 9300 for a free consultation before paying penalties that may qualify for removal.

Live References

Tax Debt Advisors: IRS Penalty Abatement

https://taxdebtadvisors.com/blog/category/it-will-get-better-everyday

Internal Revenue Service: Administrative Penalty Relief

https://www.irs.gov/payments/administrative-penalty-relief

Internal Revenue Service: Automatic Exemption From Penalty

https://www.irs.gov/newsroom/automatic-exemption-from-penalty-what-taxpayers-should-know

Internal Revenue Service: Reasonable Cause Penalty Relief

https://www.irs.gov/payments/penalty-relief-for-reasonable-cause

Internal Revenue Service: Form 843
https://www.irs.gov/forms-pubs/about-form-843
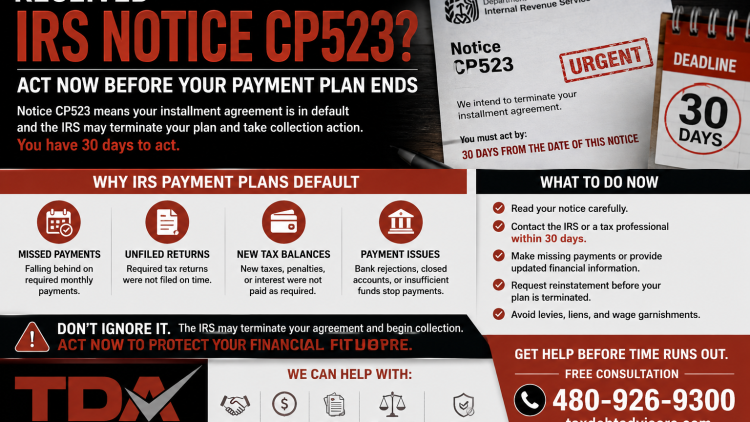
Understand IRS Notice CP523, the 30 day deadline, reinstatement options, and possible collection action.
Written by Craig B

IRS Notice CP523: What To Do Before Your Payment Plan Ends

What Does IRS Notice CP523 Mean?

An IRS payment plan can create breathing room, but it does not run on autopilot. A missed payment, unfiled return, or new unpaid tax balance can place the arrangement in default. The first clear warning may be IRS Notice CP523.

CP523 is serious because the IRS is proposing to terminate the installment agreement. It also warns that collection action may follow if the problem is not corrected. The notice should not be ignored or treated as an ordinary monthly bill.

Read the Reason and Deadline First

The notice explains why the IRS considers the agreement to be in default. It also provides a termination date and a telephone number for the department handling the account.

The IRS advises taxpayers to respond as soon as possible and no later than 30 days from the notice date. Waiting until the final days can make it harder to gather records or correct a payment problem.

Check the tax periods, balance, recent payments, and contact information. Keep the envelope and copy every page. When a payment was made recently, collect the confirmation number, bank statement, or cancelled check before calling.

Understand Why Payment Plans Default

A missed monthly payment is one common reason, but it is not the only one. Taxpayers in an installment agreement must remain current with future filing and payment obligations. A new unpaid balance, late return, missed estimated payment, or unpaid federal tax deposit can put the agreement at risk.

Direct debit problems also happen. A closed account, changed routing number, insufficient funds, or bank rejection can interrupt a payment even when the taxpayer believed everything was current.

Compare the notice with account records and recent activity rather than assuming either the IRS or the taxpayer must be correct.

Correct the Problem Before the Agreement Ends

The IRS says making the required payment before the termination date may prevent the agreement from ending. In other cases, the taxpayer may need to contact the IRS and request reinstatement.

Reinstatement can involve a user fee, updated financial information, or payment of a new tax liability. The correct approach depends on why the default occurred and whether the original monthly amount is still affordable.

Someone whose income has fallen should not promise a payment that cannot be maintained. The IRS states that a changed financial condition may support a lower monthly amount, although documentation may be requested.

Do Not Ignore the Levy Warning

When no action is taken, the IRS may terminate the agreement and resume collection. That can include a Notice of Federal Tax Lien or a levy against wages and bank accounts.

An immediate levy does not normally occur the day the notice arrives. IRS rules generally restrict levy action while an installment agreement remains in effect, for 30 days after termination, and while a timely appeal is pending. Those protections provide time to act, not a reason to wait.

Know When an Appeal May Be Available

A taxpayer who disagrees with the proposed termination can speak with the IRS using the number on the notice. When the disagreement remains unresolved, appeal rights may be available through the IRS Independent Office of Appeals.

An appeal should be supported by records. A payment may have posted incorrectly, a return may not have been recorded, or corrective action may already be complete. The taxpayer should still call after fixing the problem so the IRS can confirm the account and consider reinstatement.

Protect the Next Agreement

Once the default is resolved, review why it happened. Update bank information, arrange reminders, file every required return, and plan for current taxes so another balance does not develop.

The monthly amount also needs to be realistic. A full financial review can determine whether a revised installment agreement or another collection alternative better fits the taxpayer’s circumstances.

Get Help With IRS Notice CP523 in Mesa

Tax Debt Advisors, Inc. has helped Arizona taxpayers resolve IRS collection problems since 1977. Scott Allen, EA, can review the notice, account history, payment records, filing compliance, and available resolution options before the deadline passes. Call 480 926 9300 for a free consultation and help responding to a defaulted IRS payment plan.

Live References

Tax Debt Advisors: IRS Payment Plans

https://taxdebtadvisors.com/blog/category/irs-tax-payment-plan

Internal Revenue Service: Understanding Your CP523 Notice

https://www.irs.gov/individuals/understanding-your-cp523-notice

Internal Revenue Service: What If I Cannot Pay My Installment Agreement?

https://www.irs.gov/newsroom/what-if-i-cant-pay-my-installment-agreement

Internal Revenue Service: Letters and Notices Offering an Appeal Opportunity

https://www.irs.gov/appeals/letters-and-notices-offering-an-appeal-opportunity

Internal Revenue Manual: Installment Agreements

https://www.irs.gov/irm/part5/irm_05-014-001r

Written by Craig B

Received an IRS CP14 Notice? What Arizona Taxpayers Should Do

Finding an IRS envelope in the mailbox can make an ordinary day feel considerably worse. A CP14 notice is serious, but it does not mean the IRS is auditing you or preparing to seize property immediately. It is generally the first bill sent after the IRS processes a return and determines that tax, penalties or interest remain unpaid.

The notice deserves prompt attention and careful review before money is sent or a payment plan is selected.

Confirm What the CP14 Notice Says

Start with the tax year, balance and payment deadline printed on the letter. A CP14 normally identifies the unpaid tax, penalties, interest and any credits already applied. The IRS generally requests payment within 21 days, although the date shown on the notice controls.

Compare the figures with your filed return, bank records and earlier IRS correspondence. A balance can arise because the return showed tax due, an estimated payment was missed, withholding was insufficient or a payment was not credited correctly.

Keep the entire notice. The identifying number, tax period and contact details may be needed if you call the IRS or ask a tax professional to review the account.

Check Whether a Payment Was Already Made

Do not assume the notice is correct merely because it came from the IRS. Processing delays and payment posting problems can occur. Sign in to your IRS Online Account and review the balance and payment history.

If a payment cleared your bank but does not appear on the account, gather proof before contacting the IRS. Useful records may include a cancelled check, bank statement, electronic confirmation number or receipt.

Paying the same amount again can create another problem. When the balance appears wrong, it is usually better to document the payment and address the mismatch than send a duplicate payment out of fear.

Pay What You Can Without Ignoring Essentials

If the balance is accurate and full payment is affordable, paying by the notice deadline limits additional interest and penalties. When the entire amount cannot be paid, a partial payment may still reduce future charges.

Do not empty an account needed for rent, food, utilities or medical care without first reviewing the available alternatives. The correct response depends on the amount owed, current income, necessary expenses, assets and whether other returns remain unfiled.

Most IRS resolution options require taxpayers to have filed all required returns. Missing returns should therefore be identified before an application begins.

Consider the Available IRS Resolution Options

A straightforward balance may be handled through a short term payment arrangement or monthly installment agreement. Taxpayers facing genuine financial hardship may need to explore a temporary collection delay, often called Currently Not Collectible status.

Penalty relief may be possible when IRS requirements are met. An Offer in Compromise can settle qualifying tax debt for less than the full balance, but it is not available simply because someone wants a lower payment. The IRS reviews income, expenses, assets and expected ability to pay.

The best option is not always the one advertised most heavily. An affordable installment agreement may be more realistic than an offer, while a person unable to meet basic living expenses may need a hardship based approach.

Do Not Let the Notice Become an Emergency

A CP14 is an early billing notice, giving the taxpayer time to verify the debt and choose a response. Ignoring it can lead to additional notices and more serious collection action later.

Note every deadline. Interest and applicable penalties generally continue while the debt remains unresolved.

Professional help becomes particularly useful when several years are involved, returns are missing, the amount appears wrong, an existing payment plan has failed or the proposed monthly payment is unaffordable.

Get Help With an IRS CP14 Notice in Mesa

Tax Debt Advisors, Inc. has helped Arizona taxpayers resolve federal tax problems since 1977. Scott Allen, EA, works directly with clients to review IRS records, verify balances and explain the available resolution choices without promising a result before the facts are known. If you received a CP14 notice or cannot afford the balance shown, call Tax Debt Advisors at 480 926 9300 for a free consultation.

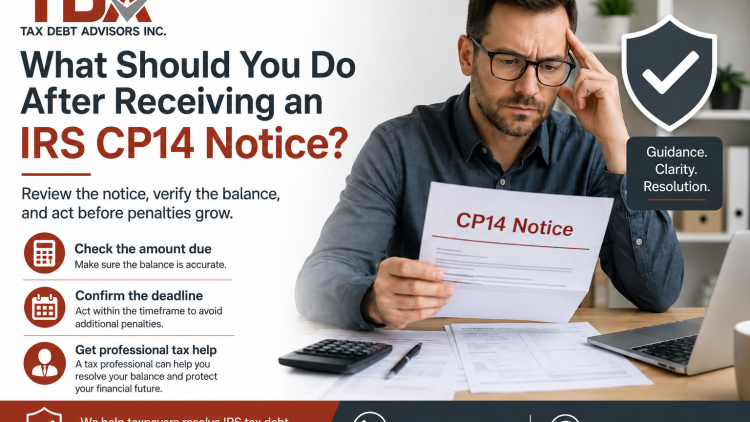
An IRS CP14 notice says you have a balance due. Learn how to verify the amount, check recent payments, and respond before the deadline.
Written by Craig B

What Should You Do After Receiving an IRS CP14 Notice?

Student loans can have various implications for federal taxes, including potential deductions, credits, and consequences for repayment. Here are some key points to consider regarding student loans and federal taxes:

  1. Student Loan Interest Deduction: Taxpayers who have paid interest on qualified student loans may be eligible to deduct up to $2,500 of the interest paid on their federal income tax return. This deduction is available even if the taxpayer does not itemize deductions, making it accessible to many taxpayers. However, there are income limitations and other eligibility criteria that must be met to claim this deduction.
  2. Education Tax Credits: Taxpayers who are paying for higher education expenses, including student loan interest, may be eligible for education tax credits such as the American Opportunity Tax Credit (AOTC) or the Lifetime Learning Credit (LLC). These credits can help reduce the amount of tax owed or result in a refund if the credits exceed the taxpayer’s tax liability.
  3. Income-Driven Repayment Plans: Borrowers who are enrolled in income-driven repayment plans (IDRs) for their federal student loans may have a portion of their outstanding loan balance forgiven after making qualifying payments for a certain period. However, the forgiven amount may be considered taxable income in the year it is discharged, potentially resulting in a higher tax liability for the borrower.
  4. Taxability of Loan Discharges: In certain circumstances, such as total and permanent disability or death, federal student loans may be discharged, meaning the borrower is no longer required to repay the remaining balance. However, the discharged amount may be considered taxable income unless an exception applies.
  5. Employer Student Loan Repayment Assistance: Some employers offer student loan repayment assistance as a benefit to employees. Under current law, employer contributions to employee student loans of up to $5,250 per year may be excluded from the employee’s taxable income, providing potential tax savings.
  6. Tax Withholding Adjustments: Borrowers who expect to have a significant tax liability due to forgiven student loan debt or other factors may need to adjust their tax withholding or make estimated tax payments to avoid underpayment penalties.

It’s important for borrowers to understand the tax implications of their student loans and to consult with a tax professional or financial advisor for personalized advice based on their individual circumstances. Additionally, tax laws and regulations may change over time, so borrowers should stay informed about any updates that may affect their tax situation.

Tax Settlement in Mesa, Arizona

If you need IRS Debt Help, Tax Debt Settlements or Tax Debt Advising in Phoenix, Mesa or anywhere else, Tax Debt Advisors can help! Give us a call at 480-926-9300 or fill out our contact form for a free consultation.

What Is a Tax Amnesty Program?
Written by Craig B

What To Do When IRS Tax Debt Starts Keeping You Up At Night

IRS tax debt has a way of getting into your head. A letter arrives, then another one. Maybe you owe more than you expected. Maybe old returns were never filed. Maybe penalties and interest have made the number feel impossible. At some point, the problem stops being only financial. It becomes stress.

The worst thing to do is panic. The second worst thing is to ignore it.

Start By Opening The IRS Notices

It sounds simple, but many people stop opening IRS mail because they are afraid of what it says. That only makes the situation harder. Notices can explain the tax year involved, the balance due, deadlines, appeal rights, missing returns, proposed changes, or collection action.

You do not have to understand every line by yourself. But you do need to know what the IRS is asking for and how urgent the deadline is.

Put every notice in one folder. Do not throw anything away. The paper trail matters.

File Missing Returns Before Chasing A Deal

If you have unfiled tax returns, those usually need attention before a real resolution can happen. The IRS wants current information before considering many collection options.

Back tax returns can feel embarrassing, but they are common. People fall behind after job changes, business problems, divorce, illness, self employment surprises, or simple fear. The important thing is to get accurate returns filed and stop the problem from growing.

A professional who handles back tax returns can help reconstruct records and bring the account closer to compliance.

Be Careful With Big Promises

Tax debt advertising can be loud. Some companies make it sound as if nearly everyone can settle for pennies on the dollar. That is not how the IRS works.

Some taxpayers may qualify for an offer in compromise. Others may need an installment agreement, currently not collectible status, penalty review, bankruptcy guidance from an attorney, or another route. The right answer depends on income, assets, expenses, tax years, compliance, and the IRS collection file.

A good tax professional should explain your actual options, not sell you a fantasy.

Work With The Person Handling Your Case

Tax debt is personal. You should know who is representing you, what they are doing, and what the next step is. Being passed from salesperson to call center to unknown case manager can make the process more frustrating.

Tax Debt Advisors works directly with taxpayers who need IRS debt help, back tax returns, and professional tax resolution guidance. The company emphasizes direct representation with Scott Allen E.A., rather than a sales driven process.

Get Help Before The IRS Gets Louder

If IRS tax debt is causing stress, do not wait for levies, liens, wage garnishment, or more notices before asking for help. Contact Tax Debt Advisors to discuss your tax debt, missing returns, and possible IRS resolution options with someone who can look at the real details.

References

Tax Debt Advisors
https://taxdebtadvisors.com/

Tax Debt Advisors About
https://taxdebtadvisors.com/about.html

IRS Payment Plans
https://www.irs.gov/payments/payment-plans-installment-agreements

IRS Offer In Compromise
https://www.irs.gov/payments/offer-in-compromise

IRS Taxpayer Bill Of Rights
https://www.irs.gov/taxpayer-bill-of-rights

Tax Settlement in Mesa, Arizona

If you need IRS Debt Help, Tax Debt Settlements or Tax Debt Advising in Phoenix, Mesa or anywhere else, Tax Debt Advisors can help! Give us a call at 480-926-9300 or fill out our contact form for a free consultation.

Common Tax Problems in Mesa AZ
Written by Craig B

First Steps To Take When You Did Not File Taxes On Time

Missing the tax deadline feels awful. Even if there is a perfectly understandable reason, illness, family stress, missing documents, money trouble, or plain overwhelm, the result is the same. The date passed, the return is not filed, and now there is that nagging feeling in the back of your mind.

The best thing to do is not freeze. The IRS generally wants taxpayers to come forward, file the missing return, and start dealing with the balance. The sooner you act, the more options you usually have.

File The Return As Soon As You Can

The first step is simple, even if it does not feel easy. File the return.

Some people delay because they cannot pay everything they owe. That is understandable, but it usually makes the problem worse. Filing late and paying late are not the same thing. The failure to file penalty is generally larger than the failure to pay penalty, so getting the return filed can help stop one part of the problem from growing.

If you are due a refund, you may not owe a late filing penalty, but you should still file. Waiting too long can put your refund at risk.

Gather What You Have

Do not let one missing form keep you stuck for months. Collect your W-2s, 1099s, business income records, mortgage interest statements, charitable giving records, medical expense records, and anything else that applies to your situation.

If you are missing wage or income documents, you may be able to get transcripts through the IRS. A tax professional can also help you reconstruct records and decide the cleanest way to move forward.

Pay What You Can

If you owe money, pay as much as you reasonably can when you file. Even a partial payment can reduce the amount that continues to collect penalties and interest.

Do not empty the grocery budget or skip rent to make a tax payment. That can create a different crisis. But if you can make a safe partial payment, it may help.

Look At Payment Plan Options

If you cannot pay in full, the IRS offers payment plans for many taxpayers. A short term or long term installment agreement may allow you to pay the balance over time instead of trying to solve everything in one painful payment.

The key is to be realistic. A payment plan only helps if the monthly amount is something you can actually keep up with.

Do Not Ignore IRS Notices

If the IRS sends a letter, open it. Read it carefully. Notices often explain the balance, penalties, deadline, or next step. Ignoring letters can lead to more stress, fewer choices, and possible collection action.

You do not have to panic over every envelope, but you do need to respond properly and on time.

Ask About Penalty Relief

Some taxpayers qualify for penalty relief. The IRS may consider reasonable cause in certain situations, and some people may qualify for first time penalty abatement if they meet the requirements.

Penalty relief is not automatic, and it does not erase the tax itself. Still, it can make a real difference if penalties have added up.

Get Help Before It Gets Bigger

A missed tax deadline is not the end of the world, but it is also not something to keep pushing aside. File the return, pay what you can, explore payment options, and get professional help if the balance is more than you can comfortably handle.

If you have unfiled returns, IRS notices, penalties, or tax debt, contact Tax Debt Advisors today. Their team can help you understand your options and take the next sensible step toward getting back on track.

References

IRS, Taxpayers Who Missed The April Filing Deadline Should File As Soon As Possible

IRS, Failure To File Penalty

IRS, Failure To Pay Penalty

IRS, Payment Plans And Installment Agreements

IRS, Get Help With Tax Debt

Taxpayer Advocate Service, Consequences Of Not Filing

Tax Debt Advisors

Tax Settlement in Mesa, Arizona

If you need IRS Debt Help, Tax Debt Settlements or Tax Debt Advising in Phoenix, Mesa or anywhere else, Tax Debt Advisors can help! Give us a call at 480-926-9300 or fill out our contact form for a free consultation. This family owned tax practice has been serving the public since all the way back in 1977!

More Articles About Taxes


TIME IS TICKING TO FILE YOUR 2025 TAXES, WHAT TO DO IF YOU HAVE NOT FILED YOUR TAXES IN APRIL 2026
Written by Craig B

TIME IS TICKING TO FILE YOUR 2025 TAXES, WHAT TO DO IF YOU HAVE NOT FILED YOUR TAXES IN APRIL 2026

If you have not filed your 2025 taxes yet and it is already April 2026, you are probably feeling some stress. That is completely understandable. A lot of people fall behind on taxes for all kinds of reasons. Maybe life got busy, maybe paperwork is missing, or maybe you are worried about how much you might owe. The important thing now is not to panic, it is to act.

For most taxpayers, the federal tax filing deadline for 2025 returns is April 15, 2026. If you have not filed yet, the worst thing you can do is keep putting it off. Tax problems usually get more expensive and more stressful the longer they sit. Taking action now, even if you are not fully ready, can help you limit penalties and get back in control.

FILE EVEN IF YOU CANNOT PAY IN FULL

One of the biggest mistakes people make is assuming there is no point in filing if they cannot pay the full tax bill. In reality, filing is still extremely important. The IRS failure to file penalty is usually much steeper than the failure to pay penalty. That means not filing can cost you more than filing and paying only part of what you owe.

If you can, file your return as soon as possible. If you cannot pay the full amount, pay what you can. Even a partial payment may help reduce how much you end up owing in penalties and interest. This is one of those situations where doing something is far better than doing nothing.

REQUEST AN EXTENSION IF YOU STILL HAVE TIME

If it is still before the deadline and you are not ready to submit your full return, you may be able to request an extension. For most people, that gives you until October 15, 2026 to file. That extra time can be helpful if you are still waiting on documents, sorting through deductions, or trying to make sure everything is accurate.

But this is the part that catches people off guard. An extension gives you more time to file, not more time to pay. If you expect to owe taxes, the IRS still wants payment by the April deadline. If possible, estimate what you owe and send in as much as you reasonably can.

Don’t let a missed deadline slide.

Even if you’ve already missed it, acting fast is still the smart move. Getting your taxes filed as soon as possible is the most effective way to stop those late filing penalties from piling up. And if you’re having a tough time, you might be able to get some relief. Taxpayers sometimes qualify for penalty waivers or payment plans, especially if they can show a valid reason for the delay.
The key is to nip things in the bud. Ignoring IRS letters or dragging your feet on your tax return can easily turn a small issue into a much bigger one later.
Even if your situation feels messy, it is usually better than you think once you begin dealing with it directly.

GET HELP BEFORE THE SITUATION GETS WORSE

If you have not filed your 2025 taxes in April 2026, now is the time to deal with it. Filing late is serious, but it is also fixable. The sooner you understand your options, the easier it becomes to make a plan. Tax Debt Advisors can help if you’re behind on your filings, worried about penalties, or staring down a tax bill that’s overwhelming. Reach out today for clear guidance and start taking charge of your tax situation.

Tax Settlement in Mesa, Arizona

If you need IRS Debt Help, Tax Debt Settlements or Tax Debt Advising in Phoenix, Mesa or anywhere else, Tax Debt Advisors can help! Give us a call at 480-926-9300 or fill out our contact form for a free consultation.

0
Can You Add To Balance Regularly of a Certificate of Deposit
Written by Craig B

What Are The Pros and Cons of a CD (Certificate of Deposit) In 2026?

You may have heard of CDs, or Certificates of Deposit, if you’ve been seeking for a safe place to put your money in 2026. Because interest rates have changed in the last several years and a lot of people are worried about the economy, CDs are back on the table.

What Is a CD, Simply Put?

Banks and credit unions provide a savings account called a Certificate of Deposit. You agree to put a set amount of money into an account for a set amount of time, which is usually between six months and five years. The bank will offer you a guaranteed interest rate in exchange.

The most important word here is “guaranteed.” Your rate stays the same for the whole term, and your principal is usually protected up to government restrictions.

The Benefits of a CD in 2026

One of the best things about a CD is that you can be sure of it. A lot of CDs are giving fixed rates that are better than those of regular savings accounts in 2026. If you want things to stay the same, knowing precisely how much interest you will earn might be comforting.

For folks who don’t like taking risks or are close to retirement, that dependability might be a big plus.

Less Risky Than Market Investments

A CD does not go up and down with the market way stocks or mutual funds do. That decreased risk could make sense for short-term goals like saving for taxes, bills that are coming up, or a planned purchase.

The Bad Things About a CD in 2026

The greatest problem with a CD is that you can’t get your money back. Most of the time, if you need to take money out before the term expires, you have to pay a penalty. That penalty can lower your principal and possibly cut into the interest you earn.

A CD might not be the greatest choice for you if you believe you might need to get to your money quickly.

Risk of Inflation

Inflation is still an issue, even when CD rates are competitive in 2026. If inflation is higher than your interest rate, the real worth of your money may not rise as much as you think.

Cost of Opportunity

When you lock in a rate, you can’t get a higher rate if rates go up later. That can be annoying when rates are fluctuating.

Are CDs the Right Choice for You?

CDs can be a good way to save money for short-term goals, for people who are risk-averse, or for anybody who wants to lower their risk. But they aren’t the best choice for emergency savings that need to be easy to get to or for long-term wealth-building plans.

Call Tax Debt Advisors right now to talk about your alternatives and make a plan that will help your finances in the future.

Tax Settlement in Mesa, Arizona

If you need IRS Debt Help, Tax Debt Settlements or Tax Debt Advising in Phoenix, Mesa or anywhere else, Tax Debt Advisors can help! Give us a call at 480-926-9300 or fill out our contact form for a free consultation.

arizona flat income tax rate 2026
Written by Craig B

2026 Arizona Flat Income Tax Rates

In the last several years, Arizona’s tax system has become one of the easiest in the country. The state still has a flat income tax system for the 2026 tax year, which means that most people pay the same proportion of their income, no matter how much they make. People and company owners can plan ahead, prevent surprises, and stay in line with state tax rules if they know how this works.

The Flat Income Tax Rate in Arizona in 2026

Arizona has a flat individual income tax rate of 2.5% for the 2026 tax year. This rate applies to all types of taxable income, whether you file as a single person, a married couple filing together or separately, or a head of household.

In Arizona, taxpayers figure out their taxable income and then use the same percentage to figure out how much they owe. This system took the place of Arizona’s old bracket structure, which taxed higher incomes at greater rates.

How to Figure Out Arizona Taxable Income

In Arizona, federal adjusted gross income (AGI) is usually the first thing that counts as taxable income. After that, you may need to add, subtract, deduct, or credit various amounts before figuring out how much tax you owe.

Some examples of changes are:

Deductions for some government perks or retirement income

Credits for things like school donations or other qualified costs

Standard or itemized deductions based on who qualifies

These changes are distinct for each taxpayer, so two people with the same income may nonetheless owe different amounts once deductions and credits are taken into account.

Who Has to Pay Arizona Income Tax?

If an Arizona resident’s income is over the minimal levels defined by the state, they must file a state tax return. People who don’t live in Arizona full-time or only part of the year may also have to pay Arizona income tax on money they make in the state.

Taxable income can include:

  • Paychecks and salaries
  • Income from business
  • Income from renting out Arizona homes
  • Some investment returns

It’s especially important for people who relocate to or from Arizona during the tax year to know the regulations for residence.

Why Arizona Chose a Flat Tax

Beginning with the 2023 fiscal year, Arizona switched to a flat income tax. Before that, the state had a system with numerous brackets. The move was meant to make filing easier and make the state more competitive when it comes to taxes. Supporters said that a flat tax would attract businesses to invest and people to move to the state, while detractors were worried about how the state would make money in the long run and how it would pay for public services.

No matter what the policy argument is, the flat tax system will still be in existence in 2026 and will still effect taxpayers all around the state.

Advice for Arizona Taxpayers

Tax preparation is still crucial, even with a flat rate. Some useful steps are:

  • Keeping track of deductions and credits all year long
  • Checking the amounts withheld to make sure you don’t underpay
  • Keeping track of business or freelancing income correctly

If you owe past taxes or have a complicated filing situation, you should talk to a tax specialist.

Flat tax systems make it easier to complete math, but they don’t do rid of penalties for filing late or not paying your taxes.

How to Get Help with Arizona Tax Problems

If you owe past taxes, are being collected on, or need help figuring out what to do, getting expert advice may make a big difference. Tax relief experts can help you set up payment plans, look into settlement possibilities, and try to pay off your tax obligation.

Tax Debt Advisors helps people in Arizona understand their rights, lower their stress, and discover real answers to their tax concerns. If you owe money to the state or federal government, getting help from a professional might be the first step in getting your finances back on track.

Tax Settlement in Mesa, Arizona

If you need IRS Debt Help, Tax Debt Settlements or Tax Debt Advising in Phoenix, Mesa or anywhere else, Tax Debt Advisors can help! Give us a call at 480-926-9300 or fill out our contact form for a free consultation.

arizona flat income tax rate 2026
Written by Craig B

2026 Arizona Tax Brackets Explained: What You Need to Know for Tax Year 2026

As the 2026 tax year gets closer, it’s important for anyone who live in Arizona, are retired, or own a business to know how the state’s income taxes work. Arizona’s tax system has evolved a lot in the last several years. It used to have a lot of different graduated brackets, but now it’s simpler. This makes it easier to do the math, but it also makes deductions, credits, and overall tax preparation more important.

Arizona’s Flat Income Tax in 2026

Arizona still has a flat state income tax rate of 2.5% for the 2026 tax year. This means that everyone who pays taxes pays the same percentage of their taxable income, no matter how much they make.

This flat fee applies to all types of filing, such as single filers, married couples who file together, married couples who file separately, and heads of household. Once you know how much money you make in Arizona that is taxable, it’s easy: multiply that by 2.5%.

How to figure out Arizona taxable income

Your federal adjusted gross income (AGI) is the starting point for Arizona taxable income. Then, state-specific additions, subtractions, deductions, and credits are made. The standard deduction is one of the most essential things you can do to minimize your tax burden. It lowers the amount of income that is taxed at the 2.5% rate.

The standard deduction levels for 2026 are likely to be about the same as they have been in recent years and will normally be around:

  • Approximately $15,750 for single filers
  • Approximately $31,500 for married couples filing jointly
  • Approximately $15,750 for married filing separately
  • Approximately $23,625 for heads of household

These deductions can lower the amount of income that is taxed by a lot, especially for families with low to moderate incomes.

Why the Flat Tax Still Needs Planning

The flat tax in Arizona makes the rate structure easier to understand, but it doesn’t mean you don’t need to plan your taxes carefully. Because everyone pays the same rate, deductions, credits, and techniques for timing income are particularly important for lowering overall tax payment.

Getting Ready for 2026

Taxpayers may plan ahead, prevent surprises, and stay compliant by knowing how Arizona’s taxes will work in 2026. Knowing how the flat tax works is very important whether you have tax debt, are getting ready for retirement, or have more than one source of income.

TaxDebtAdvisors.com can help you with Arizona income taxes or other tax-related problems. They can give you professional advice that is specific to your case, which will help you reduce risk and make smart financial choices.

Keywords: Arizona tax brackets 2026, Arizona state income tax, flat tax Arizona, 2026 Arizona tax planning, Arizona income tax rates
Tax Settlement in Mesa, Arizona

If you need IRS Debt Help, Tax Debt Settlements or Tax Debt Advising in Phoenix, Mesa or anywhere else, Tax Debt Advisors can help! Give us a call at 480-926-9300 or fill out our contact form for a free consultation.

1 2 3 … 7